
Buying a house in an HOA means you become a member of the association the day you take title. You pay its assessments and you agree to follow its recorded rules for as long as you own the home. Before you make an offer, find out what the dues are and what they cover, what the rules restrict and how healthy the association’s finances are.
This guide explains what to expect and how to weigh the trade-offs. When you are ready to read the paperwork, the section on documents to review before you buy goes through them one by one.
Options to Weigh When Buying a House in an HOA
Home shoppers already juggle location, size, style and price. An HOA adds one more question: do you want to share costs and rules with your neighbors? For some people the answer is an easy yes. A board looks after the common areas, the neighborhood keeps a consistent look and there are ways to get involved. Other buyers decide the rules and the recurring cost are not for them. Neither answer is wrong, but it is much better to decide before you buy than after.
- What you get: maintained common areas, shared amenities such as a pool or clubhouse, and in some communities landscaping or exterior maintenance for your own home.
- What you give up: a monthly, quarterly or annual payment on top of your mortgage, and some freedom over paint colors, fences, parking, pets, rentals and similar choices.
- What you share: decisions. An elected board of owners runs the association, and the big questions go to a vote of the members.
What to Expect From Your HOA

Share this infographic: Pinterest · Facebook · LinkedIn · Email · Download

Membership Is Mandatory
If the home sits inside a mandatory association, membership comes with the deed. You cannot opt out, and you do not sign up separately. The obligations are written into the recorded covenants, conditions and restrictions (CC&Rs), and they bind every owner, including the next one after you. Our article on governing documents explains how the CC&Rs, bylaws and rules fit together.
Dues Are Not Optional
Every owner pays regular assessments, usually called dues. The amounts vary a great deal from one community to the next. As a rule, the more the association maintains, the more it charges. A condominium association that insures and repairs the buildings will cost more than a neighborhood association that only maintains an entrance and a park.
The Consumer Financial Protection Bureau notes that HOA dues are usually paid directly to the association and not through your mortgage payment, so you need to budget for them separately. Your lender still counts them when it decides how much you can borrow. See your mortgage and the HOA for how that works.
Ask how often the dues have gone up in recent years and what the governing documents and state law say about increases. Ask also about special assessments, which are extra charges for a large repair or a budget shortfall. An approved or likely special assessment is a cost of buying the home, even though it does not appear in the listing price.
Some HOA Costs Show Up at Closing
Dues for the month or quarter of the sale are normally prorated between the seller and the buyer, the same way property taxes are in a standard transaction. Depending on the community and the state, you may also see a transfer fee, a move-in fee, a fee for the association’s resale documents or a one-time contribution to the association’s reserves or working capital. These items become part of your closing costs. Ask your escrow or title officer for the list early so that nothing surprises you in the final week.
The Rules Come With the House
Read the rules while you can still walk away. Look for anything that conflicts with how you plan to live, from a work truck or a large dog to a home business or renting the home out later. If a rule matters to you, do not rely on what a neighbor or the listing says. Find it in the documents, using the checklist below.
Documents to Review Before You Buy
Your first job as a buyer is to ask questions. Before you commit, you should know the current dues, what they pay for, who serves on the board and how well the reserves are funded. The association’s documents answer most of those questions. Read them for three things: what you will be allowed to do, what you will pay now and what you are likely to pay later.

Share this infographic: Pinterest · Facebook · LinkedIn · Email · Download
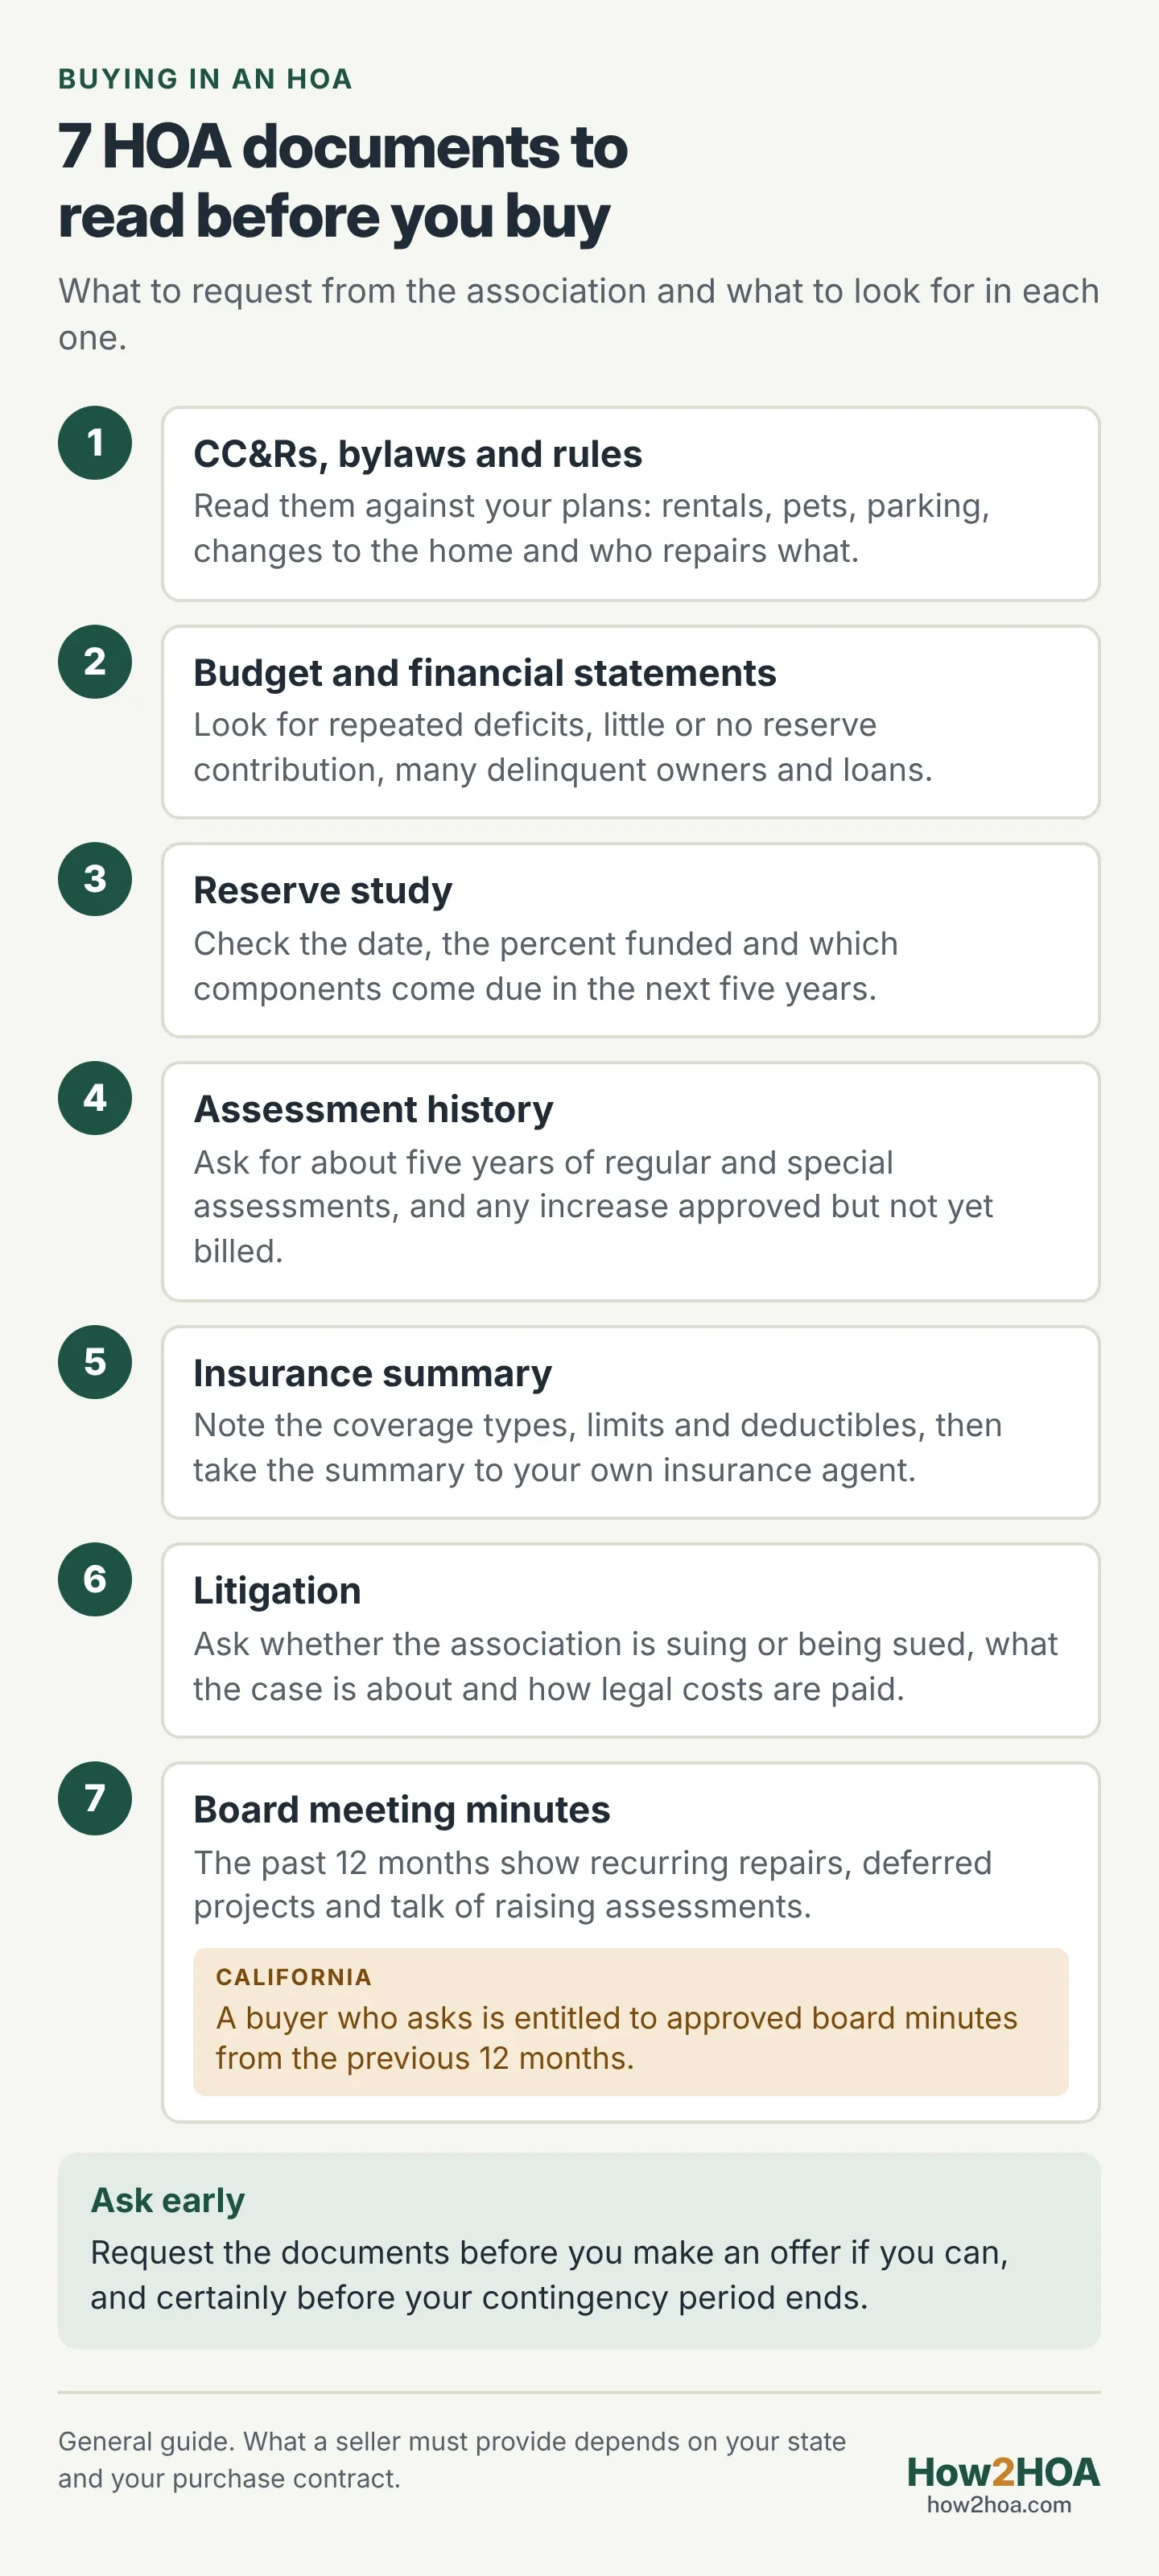
When to Ask for the Documents
Ask as early as you can, ideally before you make an offer and certainly before your contingency period ends. Once you own the home, you cannot decline the rules or the assessments. Talk to your agent about writing your offer so that you have time to review the association documents and can withdraw if they reveal a problem. How that works depends on your state and your contract.
CC&Rs, Bylaws and Rules
The CC&Rs set the restrictions, the bylaws cover how the association is run and the rules fill in daily details. Read them against your actual plans:
- Rentals. Is renting allowed? Is there a cap on the number of rentals, a minimum lease term or a waiting period?
- Pets. Number, size and breed limits.
- Vehicles and parking. Work trucks, RVs, boats, guest parking, garage use.
- Changes to the home. What needs architectural approval: paint, fences, solar, patio covers, flooring in an upstairs condo, additions.
- Maintenance split. Who repairs the roof, exterior walls, windows, plumbing, balconies and fences. This varies widely, especially between condominiums and single-family communities.
Make sure you have the current versions, including amendments.
The Budget and Financial Statements
The budget shows what the association plans to collect and spend this year. The financial statements show what actually happened. Look for:
- Whether last year ended with a surplus or a deficit, and whether deficits repeat.
- How much of each assessment goes to reserves. A budget with little or no reserve contribution is a warning.
- Delinquencies. If many owners are behind on assessments, the rest carry the shortfall.
- Loans. An association repaying a bank loan has committed part of future assessments already.
The Reserve Study
Reserves are the savings an association sets aside for large, predictable repairs and replacements. They are funded by the owners’ money, which will soon include yours. When reserves are thin, the usual results are special assessments, steep dues increases or repairs that keep getting put off.
A reserve study lists the major components the association must repair or replace, such as roofs, paving, paint, fences, elevators and pool equipment, with each item’s remaining life and estimated cost. It then compares the money needed with the money saved. Check three things:
- The date. An old study understates today’s costs.
- The percent funded. This is the reserve balance divided by the amount the study says should be on hand by now. There is no universal passing score, but a low figure combined with big items due soon means higher assessments or a special assessment is likely.
- The next five years. See which components come due and whether the funding plan covers them. Then walk the property. If the study says the roofs have ten years left and you see patches and stains, ask questions.
If a small association has no reserve study, look harder at the budget and ask how it plans to pay for its next big repair. For more on how these studies work, see understanding HOA reserve studies. For background on who prepares them, see what a reserve specialist does.
Assessment History
Ask for the regular assessment amount for each of the past five years or so and a list of special assessments over the same period. Steady, moderate increases usually mean the board is keeping up with costs. Flat dues for years followed by a large jump, or repeated special assessments, suggest the board delayed. Also ask whether any increase or special assessment has been approved but not yet billed, because you would be the one paying it.
Insurance
Get the association’s insurance summary or certificate. Note the types of coverage, the limits and the deductibles. A high deductible matters because the documents may let the association pass it to owners after a loss. Check whether the policy covers only the common areas and building shell or also the interior of units, since that decides what your own policy must cover. If the home is in an area exposed to earthquake, flood or wildfire, ask whether the association carries that coverage. Take the summary to your own insurance agent before closing. See what HOA insurance covers.
Litigation
Ask whether the association is suing anyone or being sued. A construction defect claim against a builder is different from a personal injury claim or a dispute with an owner, and each carries different risks. Find out what the case is about, whether insurance is covering the defense and how legal costs are being paid. Pending litigation can also affect financing, particularly for condominiums, so tell your lender early. Our article on your mortgage and the HOA explains what lenders ask associations.
Meeting Minutes
Board minutes from the past 12 months are the most candid document you will get. They show what the board is dealing with before it reaches the budget. Read for:
- Recurring repairs, such as leaks, plumbing failures or drainage problems.
- Discussion of raising assessments, borrowing or a special assessment.
- Deferred projects and the reasons given.
- Rule changes under consideration, especially on rentals or parking.
Questions About the Specific Home
The association’s health is one question. The status of the home you are buying is another.
- Are there unpaid assessments, fines or late charges on the seller’s account? These should be cleared at closing.
- Are there open violation notices? An unresolved violation can become your problem as the new owner.
- Were past alterations approved? Ask for the approval letters for additions, patio covers, window changes and similar work.
What to Do With What You Find
Few associations are perfect, and one weak spot is not always a reason to walk away. A known special assessment can be negotiated into the price or paid by the seller. An unclear answer can be put to the manager in writing. Several problems together, such as low reserves, visible deferred maintenance, rising delinquencies and a lawsuit, deserve real caution. If you are unsure how to read the financials, an accountant or a real estate attorney familiar with associations can review them for a modest cost compared with the purchase.
Your Responsibilities as a New Homeowner in an HOA
Know Who Maintains What
Find out what the association maintains and what is left to you. Suppose your roof starts to leak. In many condominium communities the roof belongs to the association, and the repair is its job. In most neighborhoods of detached homes, the roof is yours. The CC&Rs decide this, not the size of the dues, so check before you assume the HOA will pay and before you hire a roofer for something that is the association’s job.
Some associations welcome new owners with a summary of services and contacts. If yours does not, ask the manager or a board member for a plain list of what your dues cover.
Board members: our free welcome letter template makes that summary easy to send.
In California
California’s Davis-Stirling Act gives buyers several protections. Our California HOA law overview explains the Act as a whole. The points that matter most to a buyer are these.
Seller disclosures. California law requires the seller to give you most of the documents above without your having to hunt for them. Under Civil Code section 4525, the owner must provide a prospective buyer, as soon as practicable before title transfers or a sales contract is signed, with:
- the governing documents;
- the most recent annual budget report and related financial documents the association distributed to members;
- a written statement from the association of current regular and special assessments and fees, and any unpaid assessments, fines or penalties on the home;
- any approved change in assessments or fees that is not yet due;
- notices of unresolved violations;
- a statement describing any prohibition on renting;
- construction defect disclosures, where they apply;
- the report from the most recent inspection of exterior elevated elements, such as wood-supported balconies, decks, stairways and walkways more than six feet above the ground.
The elevated element inspection report has been on the list since January 1, 2026. Board minutes are on the list only if you ask. The statute entitles a buyer who requests them to the approved minutes of board meetings from the previous 12 months, excluding executive sessions. Ask for them in writing.
The annual budget report. The annual budget report itself must contain the operating budget, a reserve summary, a summary of the reserve funding plan, a statement of any anticipated special assessments, details of outstanding loans and an insurance summary showing limits and deductibles (section 5300).
Balcony inspections. The balcony inspection requirement applies to condominium buildings with three or more attached units and calls for a visual inspection of a sample of those elements by a licensed structural or civil engineer or architect at least once every nine years (section 5551).
Reserve studies. At least once every three years, the board must have a reserve study done that includes a visual inspection of the major components the association maintains, when their replacement value is at least half of the association’s gross budget, not counting reserves. The board must review the study every year (Civil Code 5550).
Limits on increases. Without approval from a majority of a quorum of the members, a board may not raise regular assessments more than 20 percent over the prior fiscal year or levy special assessments that total more than 5 percent of that year’s budgeted gross expenses (Civil Code 5605). Defined emergencies are an exception (Civil Code 5610).
Ask Questions and Get Help
Buying a home is a lot to manage, with or without an HOA. You do not have to sort out the association side alone. Your agent and your escrow or title officer handle these documents regularly. The association’s manager or a board member can explain how things work day to day. Neighbors can tell you what the paperwork cannot: whether the board communicates, whether repairs get done and whether meetings are civil.
If you move in and find that the pool or the landscaping is not what you hoped for, remember that the board is made up of owners like you. Go to the meetings, volunteer for a committee, and when you are eligible, run for the board. Your bylaws and state law set who can serve. You can find more on day-to-day life in an association in our section on living in an HOA.
The Law Behind This Article
Every legal point in this article comes from the official text. Each link below opens it in a new tab.
Civil Code sections: 4525 · 5300 · 5550 · 5551 · 5605 · 5610
Other sources: CFPB: Are condo/co-op fees or HOA dues included in my monthly mortgage payment?
This article is general educational information, not legal or financial advice. Laws vary by state and your association’s governing documents control many of these questions, so check with your association’s attorney or another qualified professional about your situation.